Home / Knowledge Center / Annuities
Annuities
Annuities: the complete guide
How annuities protect savings and create income, what they cost, and when they make sense.
Why annuities
Growth potential
Earn a fixed rate or interest linked to an index, growing tax-deferred.
Protection
Fixed and fixed indexed annuities aren't exposed to market losses.
Income for life
Turn savings into a paycheck you can't outlive, now or later.
How an annuity works
- 1Fund it
A lump sum, a 401(k) or IRA rollover, or deposits.
- 2Accumulation phase
Your money earns interest, tax-deferred.
- 3Choose how to use it
Withdrawals, a lump sum or income for a set period.
- 4Distribution phase
Turn it into lifetime income if you choose.
- 5Leave a legacy
Remaining value passes to your beneficiaries.
Which annuity fits your goal?
Savings can run out. Lifetime income can't.
How a surrender schedule works
Layers of protection behind a fixed annuity
Annuity vs. CD vs. bond fund
| Fixed / MYGA annuity | Fixed indexed annuity | Bank CD | Bond fund | |
|---|---|---|---|---|
| Principal protected | ✓ by insurer | ✓ by insurer | ✓ FDIC up to limits | ✗ can lose value |
| Growth | Guaranteed rate | Index-linked, cap & floor | Fixed rate | Varies |
| Taxes | Tax-deferred | Tax-deferred | Taxed yearly | Taxed yearly |
| Lifetime income option | ✓ | ✓ with rider | ✗ | ✗ |
| Early access | ~10%/yr free; surrender charges | ~10%/yr free; surrender charges | Early withdrawal penalty | Any time, at market value |
| Before 59½ | IRS 10% penalty on gains | IRS 10% penalty on gains | None | None |
Annuities and long-term care
Many fixed and fixed indexed annuities waive surrender charges if you're confined to a nursing home, and some income riders raise your payments if you can't perform daily activities. That makes an annuity part of a long-term care plan, not just a retirement plan.
Estimate care costs in your stateShort answer: an annuity is a contract with an insurance company. You deposit money, it grows tax-deferred, and later it can pay you income for a set period or for life. Fixed and fixed indexed annuities protect your principal from market losses.
How an annuity works
- Fund it with a lump sum, a 401(k) or IRA rollover, or a series of deposits.
- Accumulate: the money earns interest, tax-deferred, while it stays in the contract.
- Use it: withdraw money, turn it into lifetime income, or pass it to beneficiaries.
Types of annuities
| Type | How it earns | Best for |
|---|---|---|
| Fixed (MYGA) | A guaranteed rate for 2–10 years | CD-style safety with tax deferral |
| Fixed indexed (FIA) | Interest linked to an index, with a cap and a 0% floor | Growth potential with no market losses |
| Immediate income (SPIA) | Converts a lump sum into income starting right away | Retirees who want a paycheck now |
| Deferred income (DIA) | Income that starts at a future date | Planning for later-life income |
Variable annuities invest in market subaccounts and require a securities license; we do not offer them. See annuity types compared.
Lifetime income riders
Many fixed indexed annuities offer an income rider. It creates a guaranteed income amount you can start later, payable for life, even if the account value runs out. Riders usually carry an annual fee.
Agent tip: Compare annuities on the income they guarantee at your planned start age, not on the headline "roll-up" rate.
Surrender charges and liquidity
- Most annuities have a surrender period of 3 to 10 years.
- You can usually withdraw about 10% per year without a surrender charge.
- Larger withdrawals during the surrender period are charged a declining fee.
- Many contracts waive charges for nursing home stays or terminal illness.
- Keep an emergency fund outside the annuity.
Taxes
- Growth is tax-deferred until you withdraw.
- Withdrawals of gains are taxed as ordinary income, not capital gains.
- Withdrawals before age 59½ may face a 10% IRS penalty, with some exceptions.
- Annuities funded with IRA or 401(k) money follow required minimum distribution rules.
- A Section 1035 exchange can move one annuity to another without current tax.
This is general information, not tax advice.
How safe annuities are
Guarantees are backed by the claims-paying ability of the issuing insurer. That is why carrier strength matters. We look at independent financial strength ratings, such as AM Best. Each state also has a life and health insurance guaranty association that provides protection up to state limits if an insurer fails.
Who should consider an annuity
| Good fit | Probably not a fit |
|---|---|
| Within 10–15 years of retirement | Needs the money within a few years |
| Wants to protect savings from market drops | Comfortable with full market risk for higher growth |
| Wants guaranteed income beyond Social Security | Has no emergency fund |
| Rolling over a 401(k) from a former employer | Already has enough guaranteed income |
Annuity vs. CD
| Fixed annuity (MYGA) | Bank CD | |
|---|---|---|
| Rate | Guaranteed for the term | Guaranteed for the term |
| Taxes on interest | Deferred until withdrawn | Taxed every year |
| Backed by | Insurer and state guaranty association | FDIC up to limits |
| Early access | Free withdrawal amount, then surrender charge | Early withdrawal penalty |
Rolling over a 401(k)
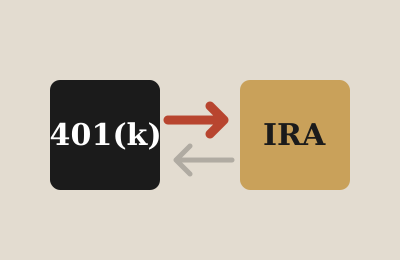
A direct rollover moves money from a 401(k) or IRA into a qualified annuity without taxes or penalties. Read the 401(k) rollover guide.
Annuities: common questions
What is the minimum to buy an annuity?
Minimums vary by carrier and product, commonly from $5,000 to $25,000 for many fixed and fixed indexed annuities.
Can I lose money in a fixed indexed annuity?
Index losses are not credited because of the 0% floor. You can lose money by surrendering early, through surrender charges, or through optional rider fees.
What happens to my annuity when I die?
Your beneficiaries receive the remaining value or a death benefit, depending on the contract and any income option you chose.
Are annuity rates going up or down?
Rates move with interest rates and change frequently. We compare current rates across carriers at the time you buy.
Can I add money to an annuity later?
Single-premium annuities accept one deposit. Flexible-premium annuities allow additional deposits.
What is the free-look period?
After delivery you have a short period, often 10 to 30 days depending on the state and product, to cancel for a refund.
What is a market value adjustment (MVA)?
Some annuities adjust the amount you receive if you surrender early, up or down depending on interest rates. Ask whether a contract has one.
How is annuity income taxed?
Earnings are taxed as ordinary income when withdrawn. Annuities funded with IRA or 401(k) money are taxed under those rules.
Can I name a beneficiary?
Yes. Beneficiaries receive the remaining value or death benefit according to the contract.
Do income riders cost extra?
Usually yes, often an annual fee that reduces the contract value. We show the fee and what it buys.
Are annuities FDIC insured?
No. They are backed by the issuing insurer, and state guaranty associations provide protection up to state limits.
How do I compare annuity offers?
Compare guaranteed values, surrender period, free withdrawal amount, caps or rates, rider fees and the insurer's financial strength.
Sources and further reading
- National Association of Insurance Commissioners (NAIC): consumer guides to life insurance and annuities
- Virginia State Corporation Commission, Bureau of Insurance: verify an agent's license
- AM Best: insurer financial strength ratings
- IRS: tax rules for life insurance and annuities
Work with TrueFin in four steps
No cost and no obligation at any step.
- 1Free consultation
A 20-minute call or video meeting about your family, business and goals.
- 2Needs analysis
We quantify your need and compare options from multiple top-rated carriers.
- 3Clear recommendation
Guaranteed values first, the trade-offs, the costs and what each option does not do.
- 4Apply and review yearly
We handle applications and underwriting, then review your plan every year.

Important information
- LIMRA, "Final U.S. Retail Annuity Sales Set New Sales High, Totaling $464.1 Billion in 2025" (2026).
- Insurance products are issued by licensed insurance companies. Guarantees are backed by the claims-paying ability of the issuing insurer.
- TrueFin Services and Nagendra (Nag) Sonti are licensed to sell life insurance and annuities in AZ, CA, FL, GA, NC, NJ, PA, SC, TX and VA. We do not sell securities, IRAs or investment advisory services.
- This page is general education, not tax, legal or investment advice. Consult a qualified professional about your situation.
- Products, riders and features vary by carrier and state and may not be available everywhere. Coverage is subject to underwriting.
- Withdrawals of earnings are taxed as ordinary income; withdrawals before age 59½ may incur a 10% federal additional tax.
- Annuities have surrender charges during a surrender period, typically several years. Optional riders carry fees.
- Annuities are not FDIC insured and are not bank deposits.
Your price is based on your age and health today.
A free 10-minute call shows exactly where you stand. Straight answers, no obligation.